📈 Wyckoff SMI “Week In Review” Nov 22nd, 2026.
📋 Market ScoreCard
| Symbol | Trend | WyckoffSMI View |
|---|---|---|
| SPY | Bearish / Weakening | Heavy selling volume confirms weakness. We believe a continued bear market may be developing, with further downside ahead. |
| QQQ | Bearish / Near Oversold | Sharp decline on heavy volume. Technometer at 39.7 suggests an oversold rally is possible, but we expect lower prices afterward. |
| TLT | Rebounding / Defensive | Strong flight-to-safety rally. We expect prices to turn lower again in the near future. |
| DX1! — U.S. Dollar | Bullish | Continued higher as expected. A short-term correction is possible before the longer-term advance resumes. |
| GDX | Bearish / Near Oversold | Sharp decline continues. We expect further weakness before a major low develops. |
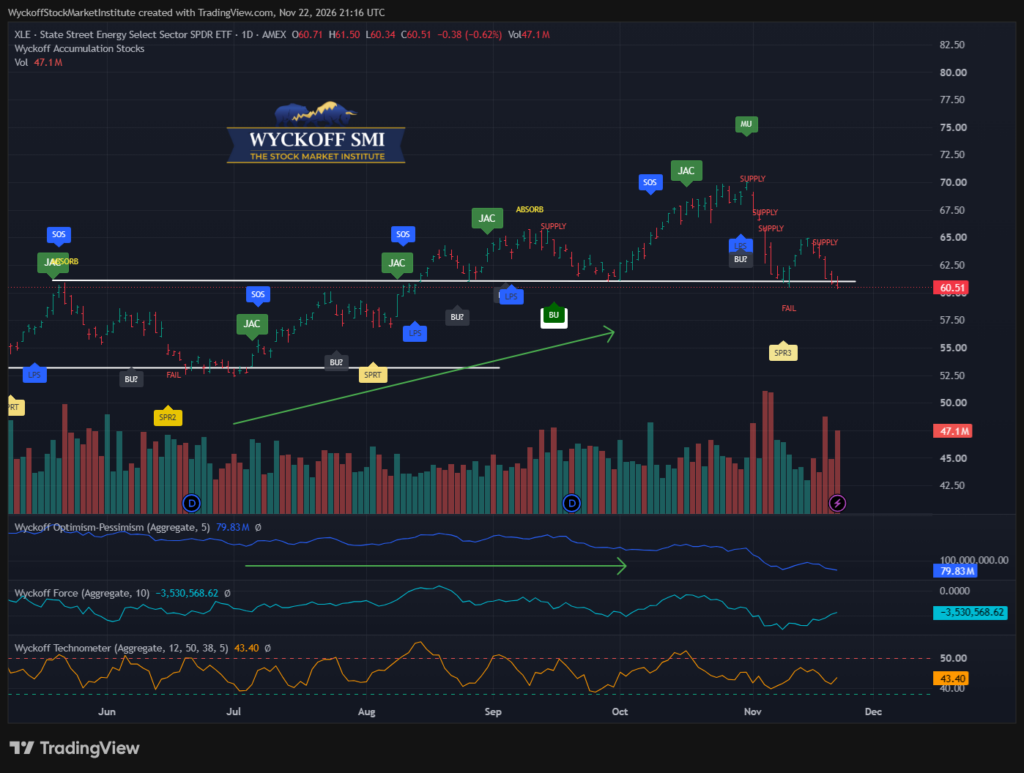
| XLE | Bullish / Testing Support | Selling pressure reached even the stronger sectors. We expect support to hold and prices to resume higher. |
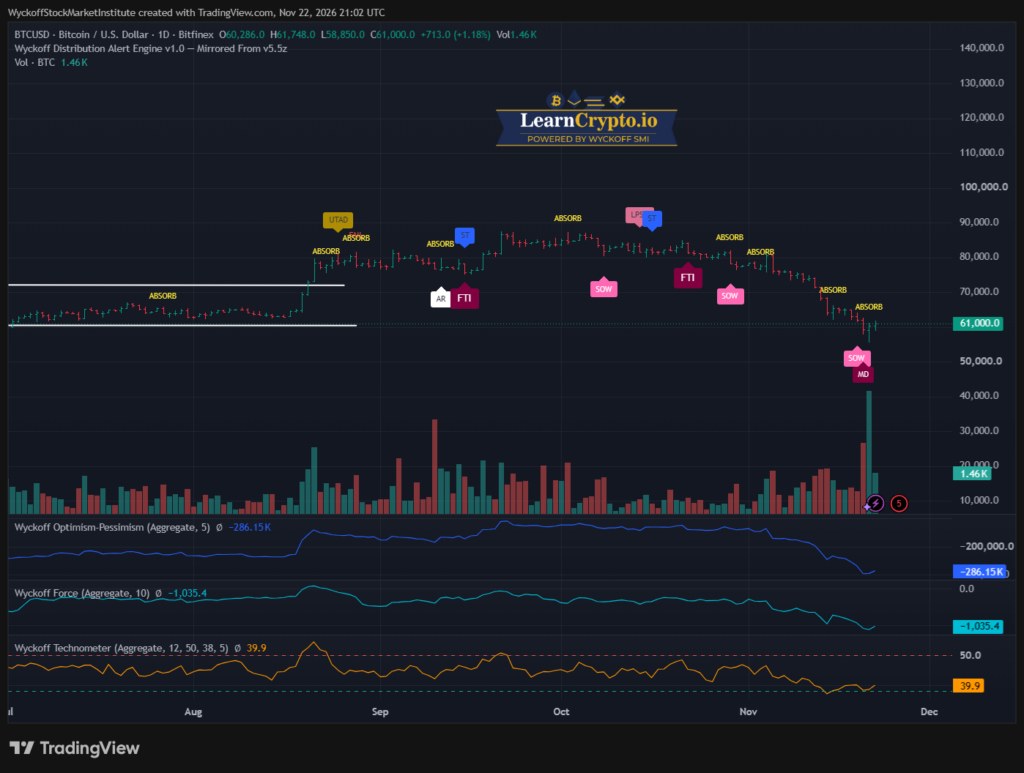
| BTC | Bearish / Oversold | Extended decline toward $60,000. A short-term oversold bounce is possible, but the broader trend remains bearish. |
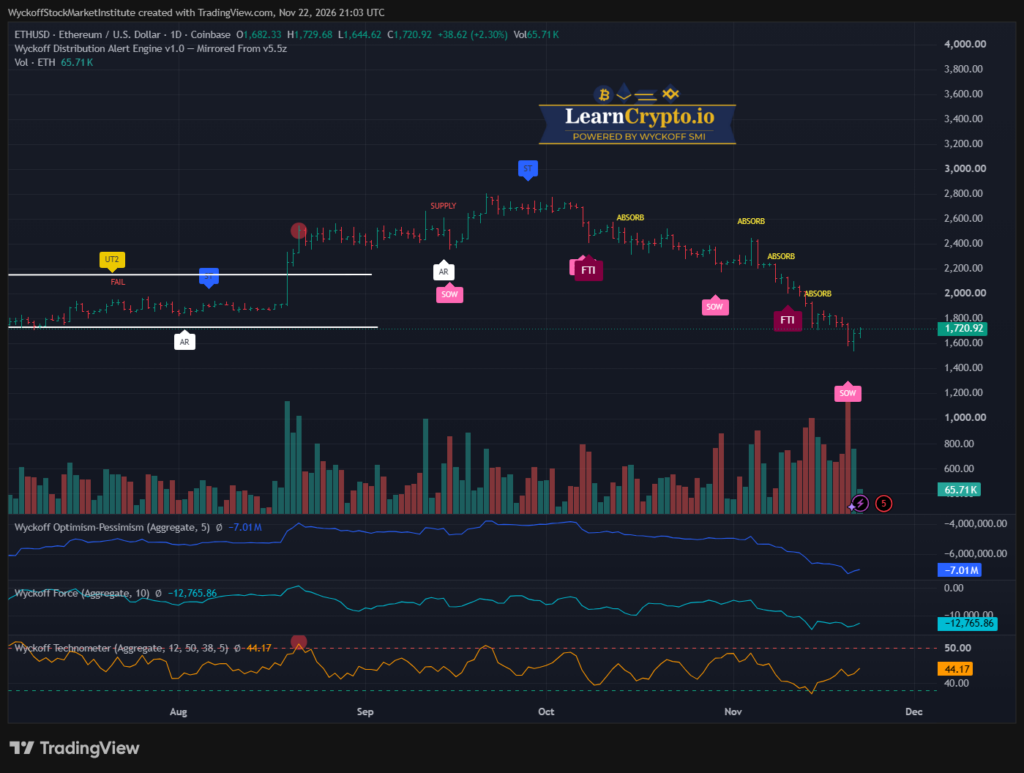
| ETH | Bearish / Recovering From Oversold | Continued sharply lower. A temporary recovery is possible, but we expect the larger bearish trend to persist. |
| XBI / IBB | Relative Strength / Improving | Biotechnology continues to demonstrate relative leadership despite broader market weakness. |
| XRT | Relative Strength / Improving | Retailers showing relative strength in our sector studies. |
| XLP | Defensive / Leading | Consumer Staples remains a leading defensive sector as investors reduce risk. |
| XLV | Defensive / Leading | Healthcare continues to demonstrate relative strength and remains among our Market Health leaders. |
🧮 Wyckoff Market Health Dashboard
Market Health Score
60 / 100
| Indicator | Reading |
|---|---|
| Health | NEUTRAL |
| Execution | HIGH |
| Trend | TRENDING UP |
| Confirmation | MIXED |
| Condition | STABILIZING |
| Leadership | XLP, XLV, XLE |
| Rotation | DEFENSIVE |
| Key Shift | Leadership mixed, no decisive shift yet |
| Cluster | TRANSITION |
| Regime | TRANSITION |
The Market Health Score remains at 60 despite significant weakness in the major averages.
While the dashboard continues to show stabilizing conditions and a positive trend classification, the recent price and volume deterioration suggests a more cautious interpretation is warranted.
The divergence between internal market readings and the weakness in SPY and QQQ deserves close attention.
We continue to prioritize actual price and volume behavior while monitoring whether the broader Market Health indicators begin confirming the developing bearish structure.
🌍 Macro Market Backdrop
The stock market experienced another week of aggressive selling, reinforcing the bearish outlook we have maintained for several weeks.
SPY and QQQ broke sharply lower, accompanied by substantial selling volume. This type of price and volume behavior raises serious concerns that the market is transitioning from a correction into a more sustained bear market.
At the same time, defensive buying supported Treasury bonds, while the U.S. Dollar continued its bullish advance.
Precious metals remained under pressure, and cryptocurrencies experienced additional liquidation.
Our Market Health Score remains at 60, reflecting a neutral internal backdrop. However, the weakness in the major averages and the defensive nature of sector rotation suggest the underlying market remains vulnerable.
🧭 Market Overview (SPY / QQQ)
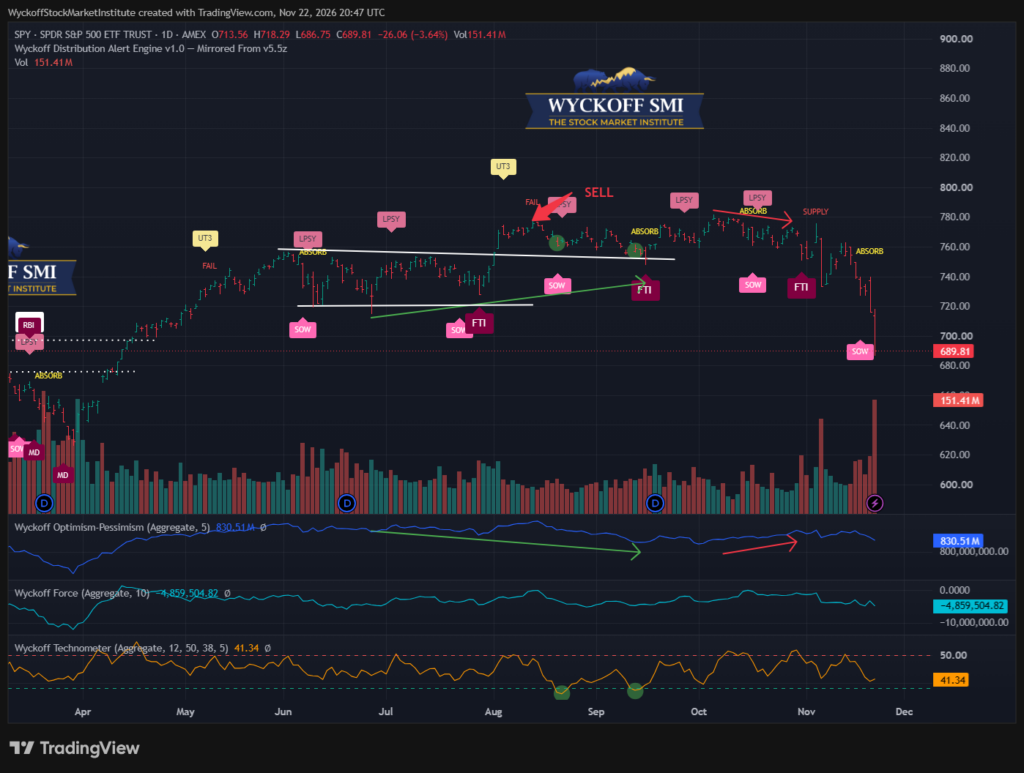
SPY was hit hard last week, just as we expected, with substantial selling volume accompanying the decline.
Friday’s close near $689.81, on approximately 151.4 million shares, reinforces our concern that institutional distribution is accelerating.
Our Wyckoff Technometer currently reads 41.34, approaching oversold territory.
Once the Technometer becomes oversold, we would expect a potentially sharp countertrend rally. However, we believe that rally will likely be temporary, followed by another move lower.
Our working outlook is that a new bear market may be developing, with prices stair-stepping lower through successive declines and oversold rallies.
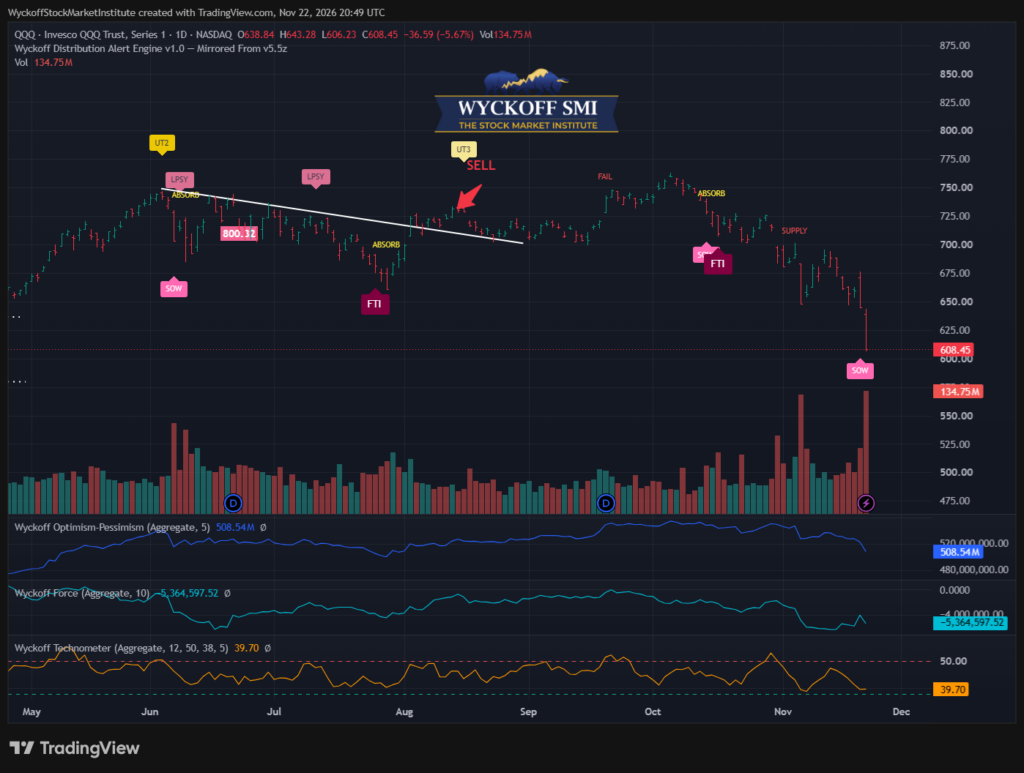
QQQ continued its sharp decline, consistent with the bearish outlook we have maintained for weeks and months.
Friday’s selling was particularly aggressive, with QQQ closing near $608.45 on approximately 134.75 million shares.
Our Technometer has fallen to 39.70, bringing QQQ very close to oversold territory.
A short-covering rally could begin at any time, but the heavy selling volume and deteriorating price structure suggest the broader trend remains bearish.
We continue looking for lower prices following any temporary recovery.
🏦 Interest Rates & Defensive Assets (TLT)
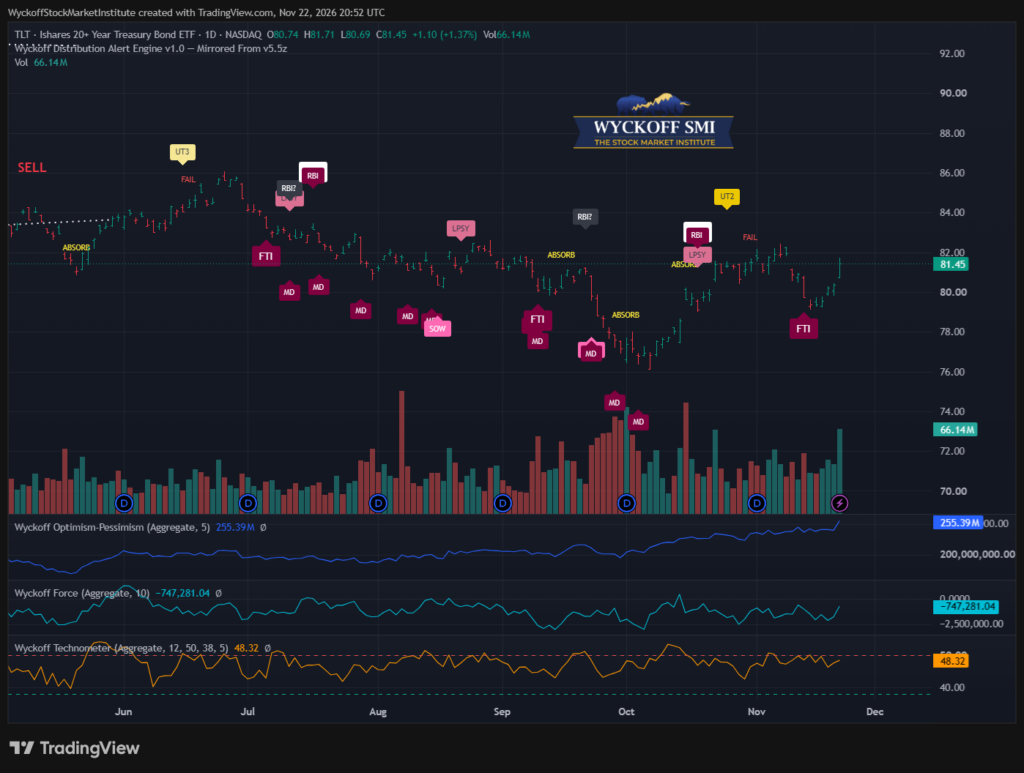
TLT experienced a strong rally last week as investors sought safety during the sharp stock market decline.
Friday’s close near $81.45, accompanied by increased volume, demonstrates the defensive demand developing in Treasury bonds.
However, we continue to believe the larger technical structure remains vulnerable.
Our expectation is that this flight-to-safety rally will eventually reverse, with TLT resuming its decline.
⛏️ Gold / Hard Assets (GDX)
The Dollar continued higher last week, reinforcing the bullish outlook we have maintained for months.
With the Dollar Index trading near 103.745, the longer-term structure remains constructive.
Our Technometer reads 48.36, suggesting the market is not at an extreme overbought reading.
Nevertheless, following the recent advance, we believe the Dollar could experience a correction lasting a couple of weeks.
We would view that weakness as temporary and continue looking for higher prices afterward.
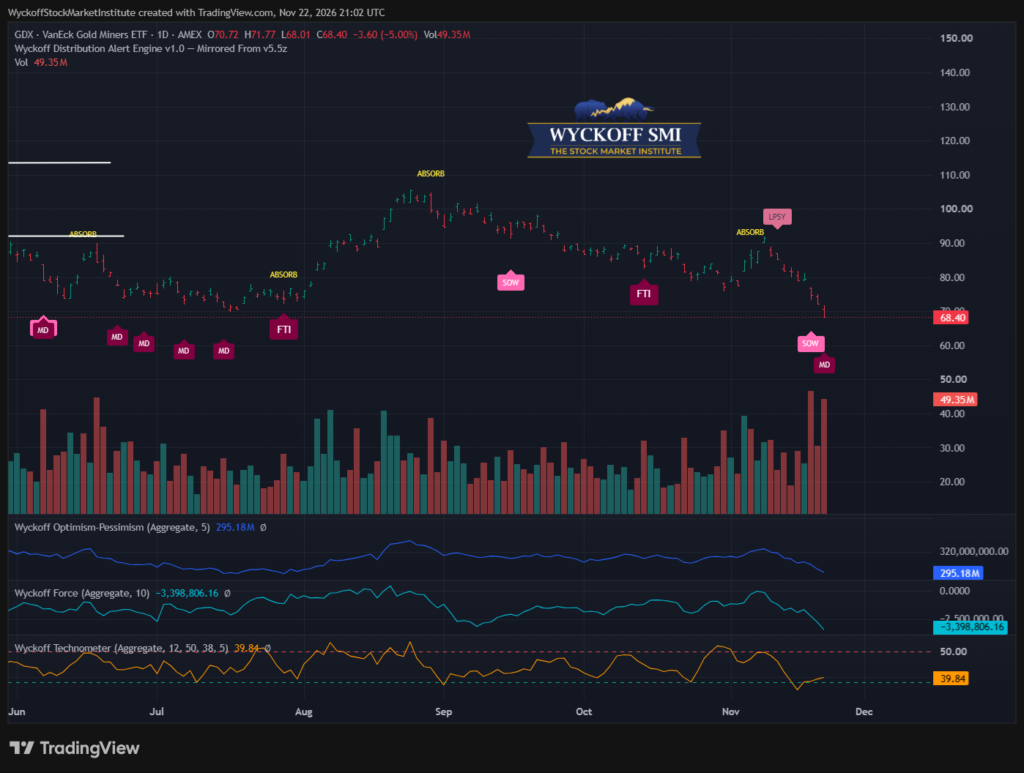
Precious metals experienced another sharp decline last week, continuing the weakness we have been anticipating.
GDX closed near $68.40, with Friday’s selling volume reaching approximately 49.35 million shares.
Our Technometer reads 39.84, placing the market near oversold territory.
Although a temporary rally could develop, we continue to believe additional downside is possible before a major low is established.
The recent selling pressure is consistent with our expectation that excessive bullish sentiment needs to be reduced before a more sustainable advance can begin.
We remain patient and continue looking for a more convincing Wyckoff accumulation structure before becoming aggressively bullish.
⚡ Energy Sector (XLE)
Even Energy experienced selling pressure last week as investors liquidated stronger positions alongside weaker holdings.
This is not unusual during aggressive market declines, when investors may sell winning positions to raise cash or cover losses elsewhere.
We continue to believe XLE’s longer-term bullish structure remains intact.
After correctly identifying important support during the previous correction, we expect buyers to respond once again.
We remain constructive on Energy and continue looking for higher prices after the current selling pressure subsides.
₿ Crypto Market Overview (BTC / ETH)
Bitcoin continued sharply lower last week, extending the decline we have been anticipating for several months.
After reaching our earlier $75,000 downside objective, Bitcoin has now fallen toward $61,000, with the chart showing an intraday low near $58,850.
The decline has been accompanied by substantial selling pressure and deteriorating readings in our proprietary indicators.
Our Technometer currently reads 39.90, following an oversold reading during the recent decline.
We believe Bitcoin could experience a short-term rally as the oversold condition is relieved.
However, the broader price structure suggests that cryptocurrencies may have entered a bear market alongside stocks.
We would currently view any recovery as a potential countertrend rally rather than confirmation of a major bottom.
Ethereum continued its decline, falling toward $1,720.92.
Our Technometer has recovered to 44.17 after approaching oversold levels.
While a temporary recovery is possible, the larger technical structure remains weak.
Selling pressure continues to dominate, and we believe Ethereum remains vulnerable to additional downside after any oversold rally.
🔄 Rotational & Thematic Notes
Sector rotation remains defensive, with Biotechnology, Retailers, Oil, and Consumer Staples showing relative strength in our sector studies.
Energy (XLE) continues to demonstrate longer-term leadership despite recent selling pressure, while Consumer Staples (XLP) and Healthcare (XLV) remain important defensive areas.
Biotechnology (XBI/IBB) and Retailers (XRT) are also showing relative strength compared with the broader market.
However, even leading sectors can experience selling pressure during aggressive market declines, as investors raise cash and reduce exposure.
Our Market Health Score remains at 60, with leadership concentrated in XLP, XLV, and XLE. Defensive rotation continues, and we have not yet seen a decisive shift toward broad-based market strength.
We remain focused on identifying which sectors hold support during the correction and demonstrate the strongest accumulation when the broader market begins to stabilize.
🧠 Tactical Outlook
Our bearish outlook on stocks continues to unfold as expected.
SPY and QQQ have experienced significant selling, and we believe the market may be transitioning into a more sustained bear market.
With Technometer readings approaching oversold territory, a sharp short-term rally could develop. However, we would currently view that rally as temporary and expect additional downside afterward.
TLT has benefited from defensive buying, but we continue looking for a reversal lower.
The Dollar remains in a bullish trend, although a short-term correction could occur before another advance.
Precious metals remain weak, and we continue looking for lower prices before a major bottom develops.
Energy remains one of our preferred sectors, and we expect important support to attract buyers.
Bitcoin and Ethereum are attempting to relieve oversold conditions, but the larger cryptocurrency structure remains bearish.
Our primary expectation is for the broader stock and cryptocurrency markets to continue stair-stepping lower, interrupted by potentially sharp oversold rallies.
👉 What We’re Watching Now
- SPY: Does the Technometer reach oversold territory and produce a sharp countertrend rally?
- QQQ: Can heavy selling volume begin to subside, or will additional liquidation develop?
- TLT: Does the flight-to-safety rally begin to reverse?
- U.S. Dollar: Will a short-term correction develop before the next advance?
- GDX: Can precious metals establish a meaningful low, or is additional downside necessary?
- XLE: Will Energy hold important support and resume its bullish trend?
- BTC: Does Bitcoin stabilize near $60,000, or will the developing bear market extend lower?
- ETH: Can Ethereum produce an oversold recovery, or will selling pressure continue?
- Sector Rotation: Do Biotechnology, Retailers, Oil, Healthcare, and Consumer Staples maintain relative strength?
- Market Health: Will the Score of 60 begin to weaken and confirm the bearish action in the major averages?
🎯 ProTraders CTA
Inside WyckoffSMI ProTraders, members receive access to our ongoing market analysis, Wyckoff Alert Engine signals, Technometer readings, sector rotation studies, and real-time trading discussions.
Our objective is to help traders recognize institutional accumulation and distribution before the larger moves become obvious.
Visit WyckoffSMI.com to learn more about ProTraders.
We don’t follow the market. We study it.
👉 Join WyckoffSMI ProTraders and trade alongside a professional Wyckoff framework:
WyckoffSMI.com

⚠️ Disclaimer
The WyckoffSMI Week In Review is provided for educational and informational purposes only and is not investment advice, a recommendation, or an offer to buy or sell any security. All commentary reflects a Wyckoff-structure interpretation at the time of publication and may change as market conditions evolve.
Investing involves substantial risk, including the possible loss of principal. Past performance is not indicative of future results. WyckoffSMI and affiliated entities may hold positions in securities discussed. Readers are solely responsible for their own investment decisions and should consult a qualified financial professional before acting.

Responses